Monday, 08:40. A replenishment board lights up in amber. The factory that used to quote sixteen weeks now sits below a buyer’s four-week ceiling, and the line under it turns green. Nobody celebrates. Down the wall, two supplier cards stay red, and the analyst responsible for them already knows the next sourcing call will not be about price. The fabric industry has changed its scoring system. This article shows what the new scoreboard measures and where the money is heading through 2033.
The Fabric Industry Reset Its Clock
Lead times collapsed. Brand replenishment requirements ran at 12 to 16 weeks before the pandemic. By 2025, the standard had tightened to 4 to 6 weeks, and the most demanding buyers hold a four-week ceiling from order to shipment. The same sourcing teams now expect a portfolio of at least three countries. Single-region dependence reads as risk, not as efficiency.
Nearshore lanes exist because of that ceiling. The Americas run 3 to 4 weeks against 10 to 16 from Asia. European nearshore supply runs 4 to 6 weeks against 10 to 14 from South Asia. Six disruptions since 2020 built this map: factory closures, eight-week extensions, and air freight costs up 300% did the persuading.
What the New Scoreboard Measures
Price still appears on every quote. It no longer wins the file alone. Tier-1 benchmarking has shifted from lowest unit cost to a composite resilience score built from five inputs:
– Cost, still first, but never alone.
– Geographic diversification, proven by a live multi-country footprint.
– Response time, measured from purchase order to shipment.
– Digital traceability, visible down to the batch.
– Sustainability compliance, documented rather than promised.
Suppliers who publish capacity, lead times, and risk data per region stay on buyer lists through 2030. The rest face progressive exclusion, quietly and without a final warning.

Capacity on the floor is now a sourcing argument, not a brochure claim.
Where the Fabric Industry Concentrates Value
The pool is still deep. The global textile market reached USD 1,160 billion in 2025 and is projected to grow from USD 1,210 billion in 2026 to USD 1,610 billion by 2033, a 4.2% CAGR. Asia Pacific held a 49.9% revenue share in 2025, and cotton remains the dominant raw material. Growth at that scale keeps attracting new capacity. What separates winners is no longer the loom count. It is the paperwork that proves the line can ship in four weeks and trace every roll.
Capacity you can audit beats capacity you are told about.
Our company profile states the numbers buyers audit: 500,000 meters of monthly capacity and 7-15 day delivery. Product details for the PET silicone leather line and the wider application range carry the same lead-time commitments.

The shortest quote on the wall is rarely the fastest one in the file.
About TOPSUN
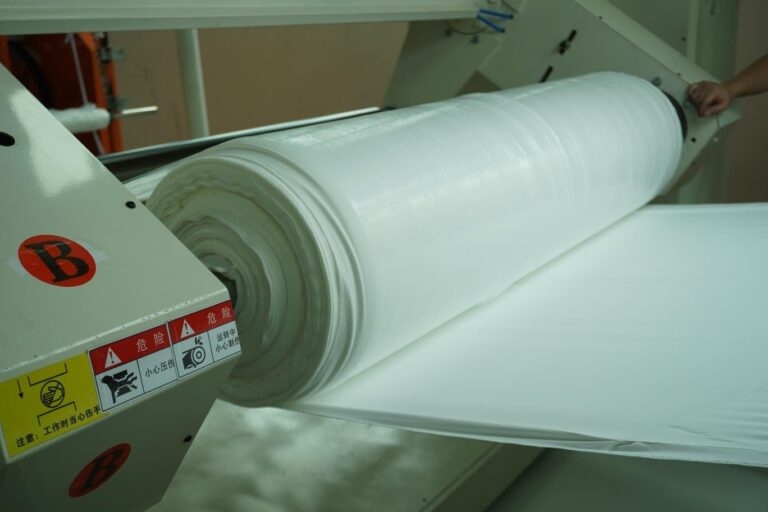
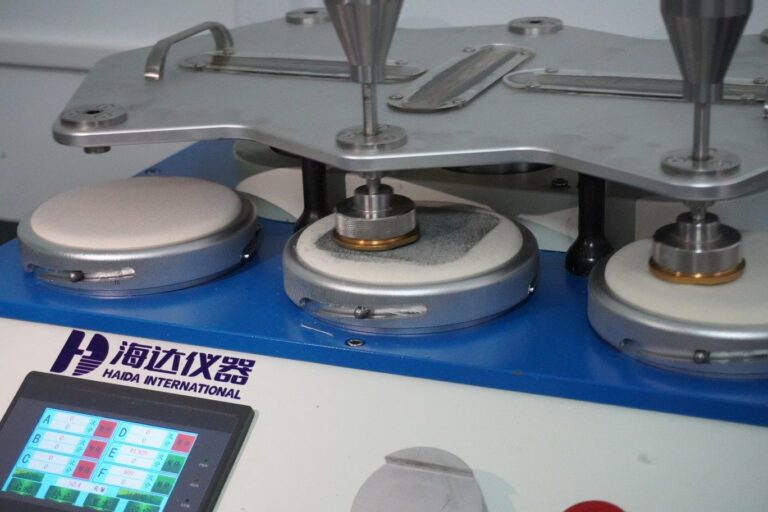
TOPSUN runs a dedicated coating and calendering facility serving automotive, furniture, healthcare, and outdoor programs in 30+ countries. Monthly capacity reaches 500,000 meters, with a 500-meter MOQ and 7-15 day delivery. Third-party inspection from SGS, BV, or TÜV is welcome before shipment.
The Quote Has Changed
The fabric industry did not lower its standards. It moved them. A four-week ceiling, a three-country portfolio, and a five-part resilience score now decide who ships and who waits. The lesson from every red card on the board is the same one: speed, traceability, and documented compliance beat the cheapest line item. Buyers who score suppliers this way in 2026 will not need to renegotiate in 2027. Their supply chains will simply keep moving.
Request Samples with Lead-Time Commitments
References
1. https://www.grandviewresearch.com/industry-anal… – Global textile market: USD 1,160B (2025) to USD 1,610B by 2033, CAGR 4.2%, Asia Pacific 49.9% share (2026)
2. https://ifactoryapp.com/industries/textile-manu… – 2026 nearshoring guide: 4-6 week replenishment standard, four-week ceiling, composite resilience score (2026)